Let us confront the most common and destructive failure in sports betting: an amateur bettor wagers $25 on a random Tuesday night baseball game, feels a sudden surge of adrenaline on Sunday afternoon, and drops $350 on the Dallas Cowboys because the game is televised on national broadcast. Within forty-eight hours, weeks of methodical analytical work are completely incinerated by a single emotional wager. If your staking size fluctuates based on your excitement level, your boredom, or the size of your television screen, you are not investing in sports markets. You are gambling recreationally, and the sportsbook will inevitably collect every dollar in your account.
The Fundamental Concept: What a Betting Unit Actually Is
In professional sports betting, monetary amounts are stripped of emotional significance and converted into standardized metrics known as "units." A unit is simply a predetermined, fixed percentage of your total dedicated betting bankroll. By converting wagers into units, sharps disconnect their emotional psychology from raw currency values, allowing them to execute their analytical process with ice-cold discipline whether their bankroll is $1,000 or $500,000.
For developing bettors, the industry consensus benchmark is straightforward: one unit equals exactly 1.0% of your total bankroll. If you have established a dedicated, isolated bankroll of $5,000, your base betting unit is $50. Conservative professional traders often operate at 0.5% to 0.75% per unit, while more aggressive retail players might stretch to 1.5% or 2.0%. Anything beyond 2.0% per wager enters reckless territory where normal statistical variance can wipe out your entire capital reserves in a single bad week.
Never risk more than 3% to 5% of your total bankroll on an entire day's card, regardless of how many attractive edges your models detect. Capital protection is your primary job description. Profit generation is merely a statistical byproduct of staying alive.
Flat Betting: The Sharp Foundation
Flat betting is the practice of wagering the exact same monetary stake—precisely one unit—on every single selection, regardless of your personal enthusiasm or subjective intuition. To the recreational gambler, flat betting sounds unimaginably boring. There are no dramatic "five-star locks of the century" and no doubling down after a frustrating bad beat. But in the real world of professional wagering, flat betting is the armor that protects you from the unpredictable buzzsaw of variance.
Consider the mathematical baseline of wagering into standard point spreads with traditional -110 juice (1.91 in decimal format). With a flat one-unit staking model, you must achieve a win rate of 52.38% simply to cover the sportsbook's commission and reach break-even. If you maintain flat sizing across 500 bets and hit 55%, you lock in a handsome, reliable return on investment. But the moment you start sizing wagers erratically—betting three units on games you "love" and half a unit on games you feel lukewarm about—your win rate becomes disconnected from your profit. Many bettors achieve a 56% win rate across a season yet lose money because their heaviest bets happened to land on the wrong side of variance.
Fixed Risk vs. Fixed Win Staking
A crucial distinction in flat betting is whether you are risking one unit or betting to win one unit. The professional standard handles this based on whether you are backing favorites or underdogs:
- On Standard Spreads and Underdogs (+100 / 2.00 or higher): Always risk exactly 1 unit. If you bet an underdog at +150 (2.50 decimal), you risk $100 to win $150.
- On Moderate Favorites (-115 to -160): Many sharps prefer to "bet to win 1 unit." If you are betting a favorite at -140 (1.71 decimal), you wager $140 to win $100. This ensures that your upside matches your baseline unit profit without over-exposing capital.
- On Heavy Chalk (-200 or shorter): Never scale up your raw capital to chase small payouts. Risking four units to win one unit on a heavy favorite exposes your bankroll to catastrophic black-swan events. If you must bet heavy favorites, keep your absolute risk capped at one unit.
Mentor Directive: Base your unit size on your starting bankroll at the beginning of an auditing cycle (such as a full calendar quarter or an entire sporting season). Never recalculate your unit size on a daily basis after individual wins or losses. Micro-adjustments invite emotional bias.
The Kelly Criterion: Mathematical Optimization vs. Real-World Danger
When you discover a massive analytical edge over the market, pure financial probability theory suggests you should bet more; when your edge is thin, you should bet less. This is the intellectual foundation of the Kelly Criterion, a mathematical formula formulated by physicist John Kelly at Bell Labs in 1956 to maximize logarithmic capital growth over long sequences of favorable bets.
The standard Kelly formula is expressed as:
f* = (b * p - q) / b

Where:
f* = The optimal fraction of your bankroll to wager
b  = The decimal odds minus 1 (the net payout ratio)
p  = Your estimated true probability of winning
q  = The probability of losing (1 - p)
Let us examine a concrete scenario. Suppose you identify a soccer underdog offered at decimal odds of 2.10 (+110). Your statistical model projects that the true probability of this team winning is 54% (p = 0.54), meaning the probability of losing is 46% (q = 0.46). The net payout ratio is b = 1.10. Plugging these figures into the formula gives:
f* = (1.10 * 0.54 - 0.46) / 1.10
f* = (0.594 - 0.46) / 1.10
f* = 0.134 / 1.10 = 0.1218 (or 12.18% of your bankroll)
The Lethal Trap of Full Kelly
Full Kelly tells you to place over 12% of your entire betting bankroll on this single match. If you actually do this, you will inevitably go broke. Why? Because the Kelly formula operates on the rigid assumption that your probability estimate (p = 0.54) is 100% accurate, objective, and devoid of error. In sports betting, that assumption is a dangerous fantasy.
Every predictive model contains estimation error, sample bias, unmodeled tactical variables, and unexpected roster news. If your model estimated a 54% win probability, but the team's true probability was actually only 50%, you held zero edge and just risked an eighth of your entire net worth on a coin flip. Furthermore, even with perfectly accurate probabilities, Full Kelly generates stomach-churning volatility: mathematical simulations demonstrate that a Full Kelly bettor will frequently suffer catastrophic peak-to-trough drawdowns exceeding 60% to 80% of their bankroll.
Fractional Kelly: The Professional Benchmark
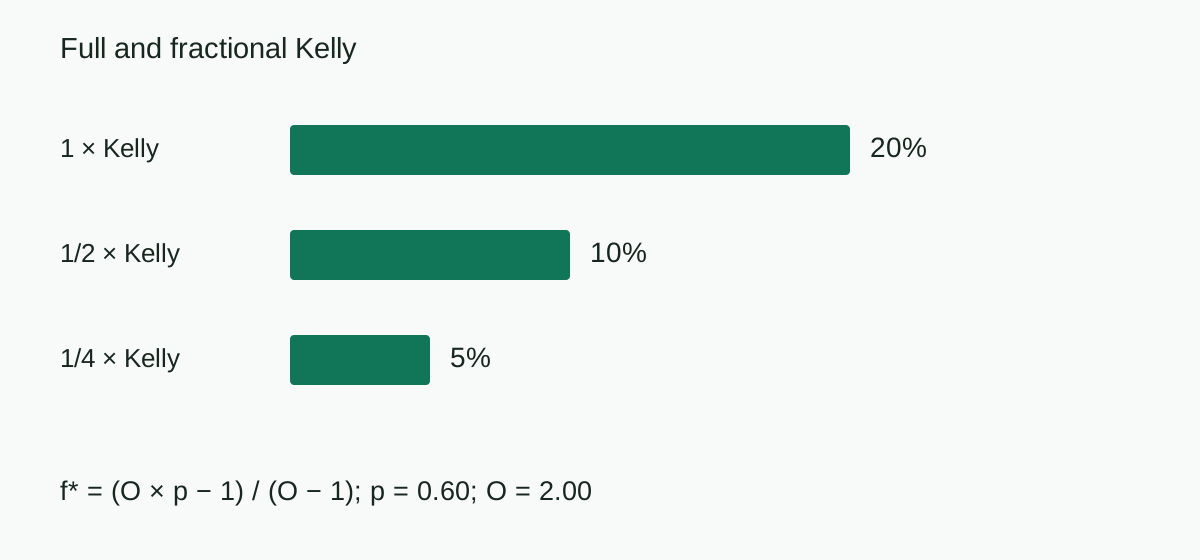
To capture the mathematical power of dynamic unit sizing without courting financial ruin, professional bettors utilize Fractional Kelly staking. The two most widely adopted industry standards are Quarter Kelly (0.25x) and Eighth Kelly (0.125x).
Under a Quarter Kelly regime, whenever the formula dictates an optimal stake, you wager exactly one-fourth of that suggested percentage. In the previous example where Full Kelly recommended 12.18%, a Quarter Kelly bettor would allocate roughly 3.0% of their roll. If Full Kelly suggested 4.0%, you would wager 1.0%.
| Staking Strategy | Compounded Growth Rate | Expected Max Drawdown | Practical Application |
|---|---|---|---|
| Full Kelly (1.0x) | 100% (Theoretical Max) | 75% - 90% (Extreme) | Unusable in real-world betting |
| Half Kelly (0.5x) | 75% of Maximum | 45% - 60% (High) | Only for verified quantitative syndicates |
| Quarter Kelly (0.25x) | 45% of Maximum | 20% - 30% (Manageable) | Sharp industry standard |
| Flat Staking (1.0%) | Linear / Stable | 15% - 25% (Controlled) | Recommended for 95% of bettors |
Notice the extraordinary trade-off illustrated in this comparison: by reducing your stake from Full Kelly down to Quarter Kelly, you sacrifice some theoretical compounding speed, but you slash your psychological stress and risk of bankruptcy by more than two-thirds. You remain firmly in the game through the deepest slumps.
Portfolio Exposure and Simultaneous Game Ceilings
A fatal blind spot in amateur staking is failing to account for aggregate portfolio risk across simultaneous matches. Suppose your models identify seven distinct NFL games on Sunday at 1:00 PM, each offering a legitimate 3% edge. If you wager 2.0 units on every game, you have 14% of your total bankroll exposed to the market at the exact same moment.
If the underdogs happen to get swept in that early time slot, you have absorbed a devastating hit to your balance before the afternoon games even kick off. To safeguard against this correlation trap, professional operators implement strict portfolio ceilings:
- Maximum Simultaneous Risk: Never permit more than 5% to 6% of your total bankroll to be active in concurrent matches occurring within the same time window.
- Proportional Downscaling: If your screening models generate ten qualified selections for a single Saturday slate, do not force full 1-unit stakes on all ten. Scale each bet down to 0.5 units or 0.6 units so that your aggregate capital at risk remains securely below your portfolio ceiling.
- Correlated Market Reductions: If you are betting both the game spread and the team total for the same squad, your outcomes are heavily co-dependent. Treat correlated positions as a single combined ticket and split your standard unit sizing across both markets.
Tiered Staking Based on Market Volatility
Not all sports betting markets possess the same distribution of variance. Wagering on an even-money NFL spread is a fundamentally different volatility environment than betting a +450 underdog in tennis or a 25-to-1 golf tournament winner. Professional traders adjust their unit allocations according to market tiering:
- Tier 1: High-Liquidity Spreads and Totals (1.80 to 2.10): 1.0 full unit. These markets represent the core volume of your portfolio. Expected hit rates range between 52% and 56%, yielding smooth equity curves.
- Tier 2: Player Props and Derivative Markets (1.85 to 2.20): 0.5 to 0.75 units. While player props offer larger raw edges due to softer sportsbook lines, sportsbook limits are lower, and late injury scratches introduce sudden variance.
- Tier 3: Moderate Underdogs (+150 to +250 / 2.50 to 3.50): 0.5 units. Because hit rates on underdogs naturally drop below 40%, keeping stakes at half a unit protects you from prolonged losing runs.
- Tier 4: Longshots and Outrights (+400 and above): 0.1 to 0.25 units. These wagers are designed to capture asymmetric upside while exposing only microscopic fractions of capital to variance.
The Ratchet Protocol: How and When to Recalibrate Your Unit
As your bankroll expands or contracts, how should your dollar unit size respond? Beginners often make the mistake of adjusting their unit after every single winning or losing day, creating an emotional rollercoaster. Sharps rely on structured recalibration milestones known as the Ratchet Protocol.
Under the Ratchet Protocol, your unit size remains completely frozen until your total bankroll achieves a meaningful milestone—typically a 20% gain. For example, if you began with a $5,000 bankroll and a $50 unit, you do not touch your $50 unit size when your roll reaches $5,300 or $5,600. Only when your balance crosses $6,000 (a +20% expansion) do you recalculate your 1.0% unit upward to $60.
Crucially, the ratchet operates with asymmetric caution during downswings. If your bankroll drops by 20% from its peak (for instance, falling from $6,000 back down to $4,800), you immediately downscale your unit size from $60 to $48. This defensive adjustment slows down capital depletion, cushions the bottom of the drawdown, and guarantees that your bankroll can never mathematically reach zero. Preserve the capital first; compounding will take care of itself.